For many hardworking families in Central Pennsylvania, the dream of homeownership feels permanently stalled by one massive financial hurdle: the down payment. When conventional mortgages require you to put down anywhere from 5% to 20% of a home's purchase price, saving up tens of thousands of dollars in cash can take years—especially while you are simultaneously paying rising rent prices.
What if you didn't need a down payment at all?
Most buyers assume that 100% financing is a thing of the past, or strictly reserved for military veterans using a VA loan. However, there is a powerful, government-backed mortgage program available to the general public that offers zero-down-payment financing. It is called the
USDA Home Loan, and it is one of the best-kept secrets in the real estate market.
At
Cody Financial Mortgage Services, we specialize in connecting buyers with loan products that actually fit their financial reality. If you are a
first time home buyer or looking to relocate out of the crowded city center, here is everything you need to know about utilizing a USDA loan to purchase your Central PA home.
1. What Exactly is a USDA Loan?
The USDA loan program is backed by the United States Department of Agriculture. Its primary purpose is to spur economic growth, promote homeownership, and improve the quality of life in rural and suburban communities across the country.
Because the federal government guarantees a portion of these loans, approved lenders are able to offer incredibly favorable terms to buyers who might not qualify for standard conventional financing. The absolute biggest advantage of the USDA loan is that it allows eligible buyers to finance 100% of the home's purchase price. You can step into a new home without draining your savings account.
2. The Location Myth: It's Not Just for Farms
When people hear "Department of Agriculture," they immediately picture buying a massive working farm, a tractor, and livestock. This is the biggest misconception surrounding the program, and it stops thousands of eligible buyers from applying.
USDA loans are for standard, single-family residential homes. The only requirement is that the property must be located in a USDA-designated "eligible rural area."
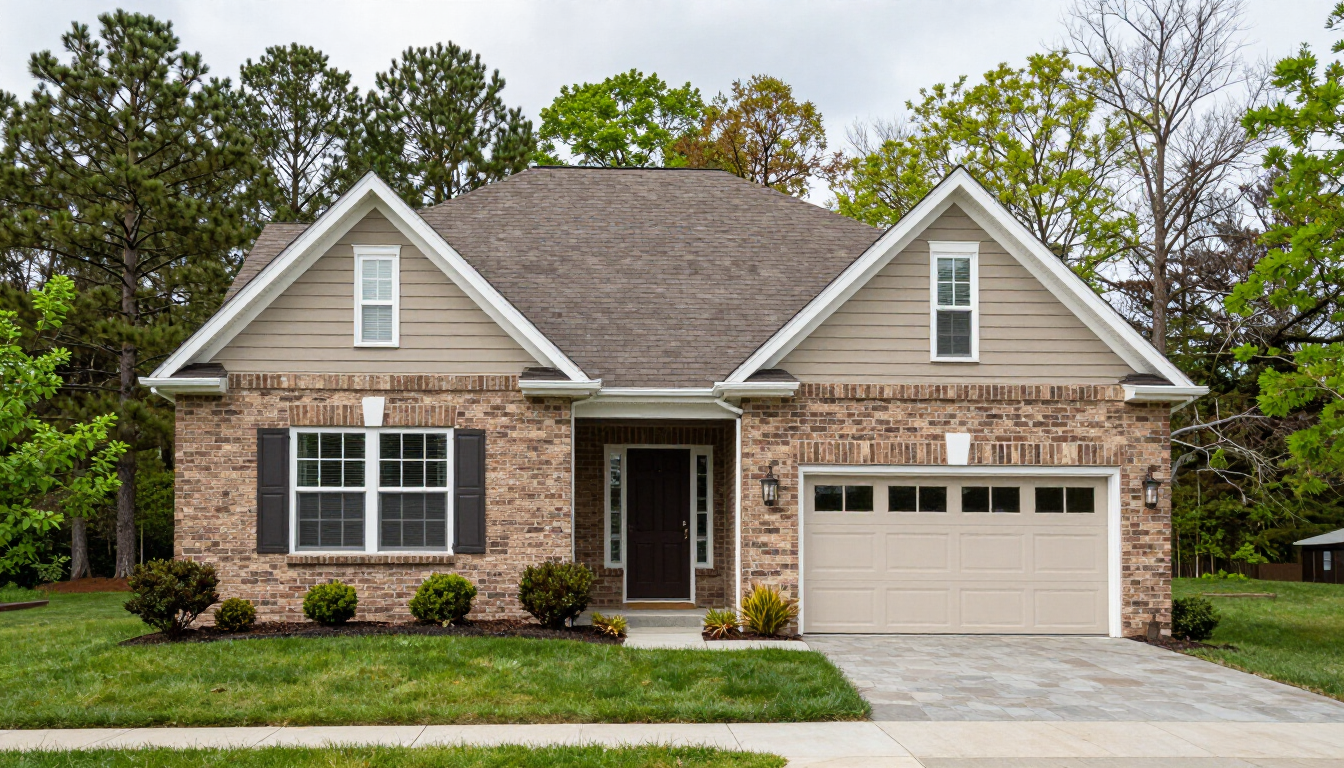
Here is the secret: the USDA's definition of "rural" is incredibly broad. While the immediate downtown centers of Harrisburg or Carlisle might not qualify, countless quiet suburban neighborhoods, developing subdivisions, and small towns located just 10 to 15 minutes outside the city limits are fully eligible. Many buyers are shocked to discover that the modern suburban home they have their eye on perfectly qualifies for 100% USDA financing.
3. Income Limits and Eligibility Requirements
Because the USDA loan is specifically designed to help low-to-moderate-income households achieve homeownership, there are strict income limits attached to the program.
You cannot make
too much money and still qualify for a USDA loan. The income limits vary heavily depending on the specific county you are buying in and the size of your household (families of five or more have significantly higher income allowances than a single buyer).
In addition to income limits, underwriters will look at:
- Credit History: While USDA loans are more forgiving than conventional loans, you generally need a credit score of 640 or higher to qualify for the streamlined automated underwriting process.
- Debt-to-Income (DTI) Ratio: Lenders want to ensure you can comfortably afford the new mortgage payment alongside your existing debts, like car loans and student debt.
4. The Benefits Beyond Zero Down
The lack of a down payment is the headline feature, but the USDA loan offers several other massive financial advantages:
- Highly Competitive Interest Rates: Because the government absorbs much of the lender's risk, USDA interest rates are routinely lower than comparable conventional mortgage rates.
- Cheaper Mortgage Insurance: If you put less than 20% down on a conventional loan, you pay hefty Private Mortgage Insurance (PMI). USDA loans do not have traditional PMI. Instead, they use an upfront guarantee fee (which can be rolled into the total loan amount) and a very small annual fee that is significantly cheaper than conventional PMI, keeping your monthly payment highly affordable.
5. Why You Need a Local Mortgage Broker
Applying for a USDA loan requires navigating specific property eligibility maps, specialized rural appraisals, and strict government underwriting guidelines. Massive national banks and online call-center lenders rarely specialize in these niche government programs. If they hit a minor paperwork snag, they will simply deny your application and move on to the next caller.
Partnering with an independent
mortgage broker changes the equation entirely. At Cody Financial Mortgage Services, we know the Central PA eligibility maps like the back of our hand. We can instantly verify if a property qualifies, help you calculate your exact household income limits, and match your application with wholesale lenders who aggressively specialize in USDA financing.
Step Into Your New Home with Cody Financial
You do not have to wait years to save up a massive down payment. A quiet suburban home, a sprawling backyard, and a mortgage payment you can comfortably afford might already be within your reach.
Whether you are looking for a zero-down USDA loan, exploring
first time home buyer programs, or considering a
mortgage refinance, we have the expertise to secure your financial future.
At
Cody Financial Mortgage Services, we are proud to serve homebuyers across Central Pennsylvania, including:
- Carlisle, PA
- Harrisburg, PA
- Camp Hill, PA
- Mechanicsburg, PA
Ready to find out if you qualify for 100% financing? Contact
Cody Financial Mortgage Services today via our website to schedule your free mortgage consultation and start your journey toward homeownership!